How Unexpected Road Incidents Impact Family Budgets
An unexpected road incident can strain a family budget long after the damaged vehicle leaves the scene. Repair bills may arrive first, but medical care, missed work, replacement transportation, and insurance deductibles can quickly increase the total. These costs belong among the common types of unexpected expenses every household should prepare to handle. Careful recordkeeping and early communication with insurers, employers, and service providers can help protect your finances during an already stressful period.
Tallying the Unseen Medical Costs
Emergency treatment is only one part of the medical bill. Follow-up appointments, physical therapy, prescriptions, medical equipment, and transportation to appointments may continue for weeks. Even families with health insurance can face deductibles, copays, and services that fall outside their plan’s network.
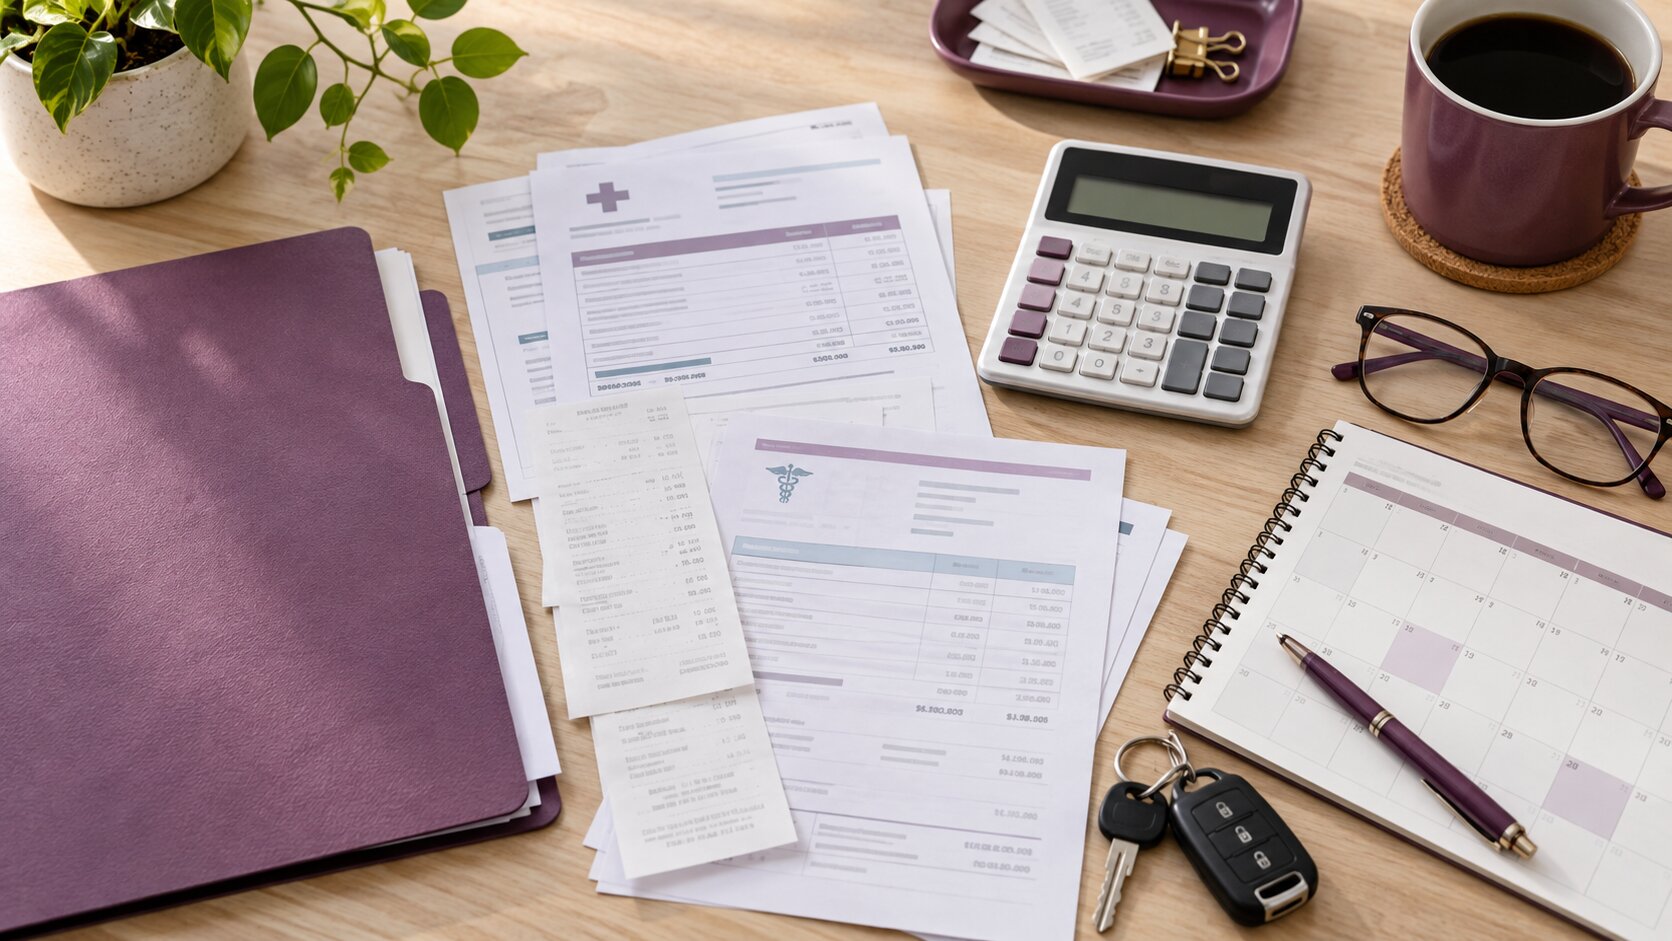
Create one folder for every statement, receipt, and explanation of benefits. Compare each bill with the insurer’s record before paying it, and ask providers about errors or duplicate charges. If a balance is difficult to cover, request a payment plan or financial assistance application. Tracking mileage to appointments and childcare costs also creates a clearer picture of the incident’s true financial impact.
Managing Time Away from Work
Lost income can be harder to calculate than a repair estimate. A parent may miss a full shift for treatment, use paid leave for follow-up visits, or reduce working hours while recovering. Another family member might also need time off to provide transportation or supervise children.
Keep copies of schedules, pay stubs, and written notes from your employer that show missed hours. Ask human resources about paid sick leave and short-term disability benefits. These records can help show how the incident affected household income during recovery.
Understanding Insurance Settlements
Insurance settlements can affect how much of the financial burden stays with your household. Before accepting an offer, confirm that you understand the deductible, repair estimate, rental transportation allowance, and any medical costs included. Early offers may arrive before doctors know how much follow-up care will be needed.
Save photographs, incident reports, repair estimates, and all correspondence with insurance representatives. Record the date, time, and subject of every phone call. Avoid guessing about injuries or expenses when answering questions. Use the documents you have and correct inaccurate information in writing. If responsibility is disputed or costs continue to grow, a car accident lawyer can review the available evidence and help determine whether the settlement reflects medical expenses, lost income, property damage, and other documented losses before you sign a release that closes the claim.
Building a Robust Emergency Plan
A dedicated emergency fund gives your family more room to handle a deductible or several days of missed income. Start with a realistic target, such as $500, then work toward one month of essential expenses. Automatic transfers after each payday can build the balance without requiring a large one-time contribution.
Your plan should also include current insurance details, emergency contacts, medication lists, and copies of key household documents. Store digital copies in a secure account that another trusted adult can access. Good family emergency preparedness also means keeping those records organized and reviewing them regularly. Check coverage limits once a year, especially after changing jobs, adding a driver, or replacing a vehicle.
Financial recovery becomes easier when every cost has a record and every deadline has a place on the calendar. A simple folder, an expense log, and a current emergency fund can keep one road incident from disrupting months of household plans.